Journie WealthTech Private Limited | AMFI Registered Mutual Fund & SIF Distributor (ARN: 318048)

The Two Words That Delayed Billions: India's Wait for Global Capital

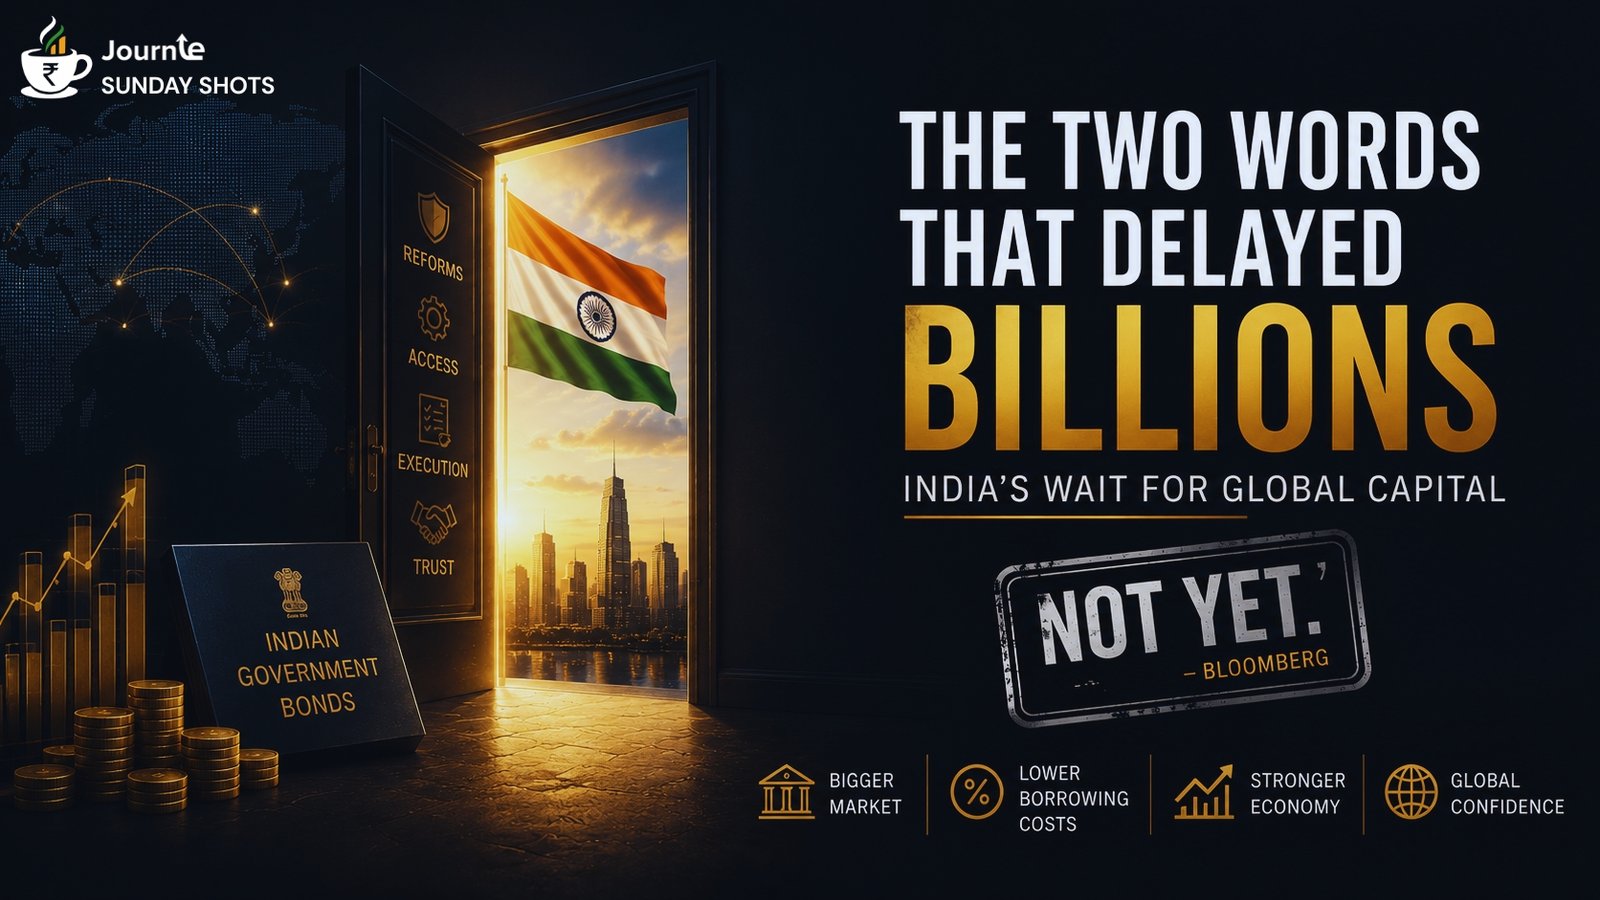
Illustration of an open doorway revealing India's future as global capital waits outside, symbolizing Bloomberg's delay in adding Indian government bonds to the Bloomberg Global Aggregate Index.

Imagine you’ve spent years building India’s finest restaurant.

You hire the best chefs. Design beautiful interiors. Source premium ingredients. Pass every safety inspection.

Then, just before opening day, Google Maps refuses to list your restaurant.

Nothing is wrong with the restaurant. Nothing has failed. You’re simply… not visible yet.

That, in many ways, is what happened to India’s bond market last week.

One decision. Two words. And billions of dollars that markets expected to flow into Indian government bonds are now waiting a little longer.

The surprising part?

The decision wasn’t made by the Indian government. Or the Reserve Bank of India. Or even any of the global regulators.

It came from a private company. Bloomberg.

Why Does Bloomberg Matter So Much?

At first glance, it seems strange.

Why should one financial software company have the power to influence global capital?

To answer that, we first need to understand something surprisingly simple:

Governments borrow money too. Just like companies. Just like individuals.

When India needs money to build highways, railways, defence infrastructure or fund its fiscal deficit, it issues Government Securities—better known as G-Secs.

Investors buy these bonds. In return, the government promises to repay the money with interest. The more investors willing to lend to India, the cheaper it becomes for the government to borrow.

Lower borrowing costs for the government eventually flow through to businesses and the broader economy.

The World's Biggest Shopping List

Most of us have heard of the Nifty 50. It’s simply a list of India’s largest and most important companies.

Many mutual funds don’t try to pick stocks. They simply buy every company that’s part of the index.

Bond markets work exactly the same way.

There are global bond indices that track government bonds from countries across the world. One of the most influential among them is the Bloomberg Global Aggregate Index (BGAI).

Think of it as the world’s shopping list for government bonds.

Thousands of pension funds, sovereign wealth funds, insurance companies and ETFs use these indices as benchmarks.

Many of these funds are passive investors. Instead of choosing countries one by one, they simply replicate the index.

That means when a country is added, these funds gradually allocate money to it in line with its weight in the index.

Bloomberg doesn’t move money itself. But the benchmarks it maintains help determine where trillions of dollars are invested.

Why Was India Missing?

Considering India is now one of the world’s fastest-growing major economies, it’s a fair question.

For years, India’s government bond market wasn’t easy for foreign investors to access.

There were investment limits. Tax rules were complicated. Settlement processes differed from global standards. Operational procedures required additional registrations and compliance.

None of these made India unattractive. They simply made India harder to invest in.

Global index providers generally prefer markets that are easy to access, easy to trade and operationally consistent.

India spent years fixing exactly those issues.

India's Long Journey

The transformation didn’t happen overnight. It unfolded over several years.

In 2020, the RBI introduced the Fully Accessible Route (FAR), allowing foreign investors to buy selected government securities without investment limits.

Over the following years, the government modernized market infrastructure, simplified access and aligned many processes with international practices.

The reforms began paying off.

In 2023, J.P. Morgan announced that eligible Indian government bonds would be included in its Government Bond Index – Emerging Markets (GBI-EM).

In 2024, that inclusion officially began in phases, bringing billions of dollars of passive foreign investment into India.

In 2025, FTSE Russell announced India’s inclusion in its Emerging Markets Government Bond Index.

Around the same time, Bloomberg also included India in its Emerging Market Local Currency Government Index.

India was no longer knocking on the door. It had started entering the room.

The Bloomberg Global Aggregate Index—one of the world’s most widely tracked bond indices.

India Made Its Final Pitch

This year, India took another significant step.

The government announced a full tax exemption for eligible foreign investors on both interest income and capital gains earned from eligible FAR government bonds.

The RBI expanded the Fully Accessible Route to include new 15-year, 30-year and 40-year government securities.

Market access became simpler. Settlement processes improved. Operational bottlenecks were addressed.

Everything appeared to be falling into place. Markets believed Bloomberg’s approval was finally around the corner.

Foreign investors began positioning themselves early. Around $6.8 billion reportedly flowed into Indian government bonds in anticipation of inclusion.

The market wasn’t waiting for the announcement. It had already started preparing for it.

Then Came Two Words

On July 31, Bloomberg published its decision – “Not yet.”

Notice what it didn’t say.

It didn’t reject India. It didn’t say India’s markets were inadequate. It didn’t ask for new reforms.

Instead, Bloomberg said that the recent reforms needed to become “firmly established in day-to-day practice.”

In simple words: “The reforms look good. Now show us that they work consistently.”

Markets reward execution—not announcements.

Why Markets Reacted Immediately

Imagine booking concert tickets months in advance because everyone expects the event to happen.

Then the organizer announces that the concert has only been postponed.

Some people continue holding their tickets. Others ask for refunds.

Markets behave in much the same way.

Many investors had already purchased Indian government bonds expecting automatic inflows after Bloomberg’s inclusion.

When the decision was delayed, some of those positions unwound. Bond prices slipped. Yields moved higher.

Nothing fundamentally changed about India’s economy overnight. Only expectations changed.

And sometimes, expectations move markets just as much as reality.

The Real Story

This story isn't really about Bloomberg. Nor is it only about government bonds.

It's about trust.

Building world-class financial markets isn't only about announcing reforms. It's about proving, every single day, that those reforms work exactly as promised.

India has spent years opening its bond market, modernizing regulations and attracting global investors.

Bloomberg's latest decision doesn't question that direction.

It simply asks for more evidence that the system performs smoothly under real-world conditions. And that is perhaps the most encouraging part.

Because when the debate shifts from "Should India be included?" to "Is India operationally ready?", the destination is no longer in doubt.

Only the timeline is.

Until next Sunday!

Disclaimer: This update is for informational purposes only. Please consult a SEBI-registered advisor before investing.

Enjoyed this week’s Sunday Shots? Share it across WhatsApp, LinkedIn, or X — and invite someone else into the conversation.
Subscribe to Sunday Shots for a fresh perspective delivered every week.

Recent Blogs

Subscribe to Journie Shots — thoughtful, well-curated insights and market stories delivered every Sunday.