Journie WealthTech Private Limited | AMFI Registered Mutual Fund & SIF Distributor (ARN: 318048)

India's $136 Billion Dollar Surprise: The Dollar-Rupee Paradox

India's $136 billion dollar surprise and the dollar-rupee paradox

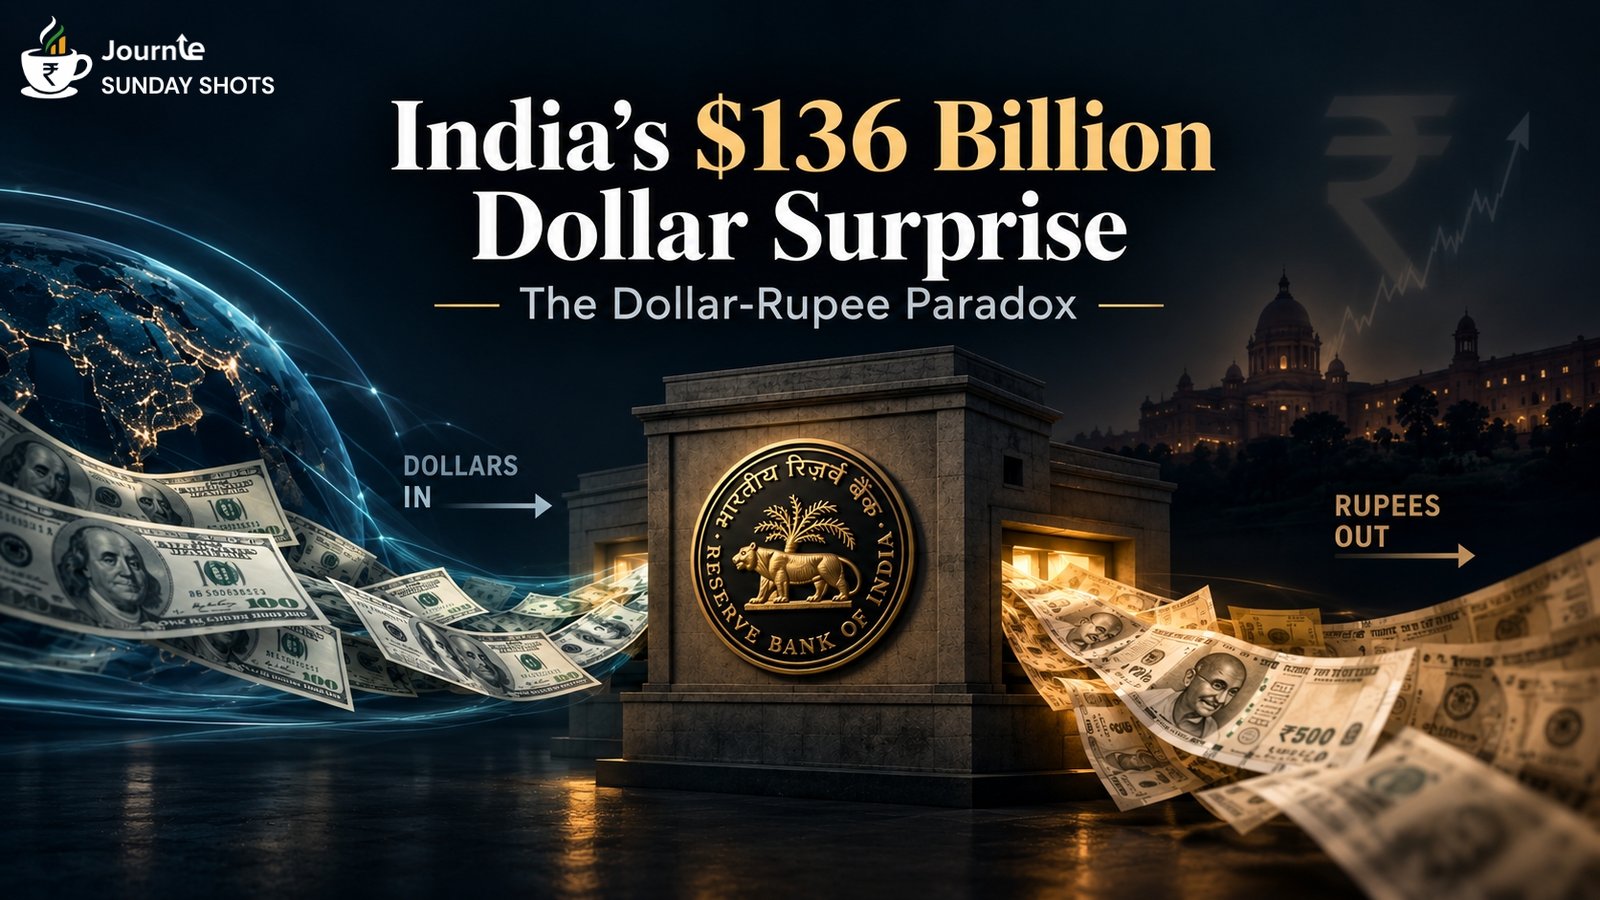
India wanted dollars. So, it built a window to bring them home.

The response was enormous. $136.4 billion flowed in.

And now, just a few months later, the Reserve Bank of India is dealing with the other side of that success: too many rupees.

More than ₹10 lakh crore of surplus liquidity is sitting in India’s banking system.

So, the RBI is now trying to pull some of that money back.

It sounds strange.

But how did India go from wanting dollars to having too many rupees?

Let’s start at the beginning.

The problem was dollars

Earlier this year, the global environment wasn’t particularly kind to emerging markets.

Oil prices were rising. Geopolitical tensions were creating uncertainty. And for India, an expensive oil bill is always a concern because a large share of its crude requirement is imported.

More dollars leaving the country to pay for imports can put pressure on the rupee.

So, the RBI had a familiar objective: Get more dollars into India.

In June, it introduced a special swap facility aimed at encouraging banks to raise foreign-currency funds through instruments including FCNR(B) deposits, external commercial borrowings and overseas foreign-currency borrowings.

The bet on foreign currency

The mechanism was fairly simple.

Banks could raise foreign-currency funds — particularly through deposits from Indians living overseas — and swap those dollars with the RBI.

The banks received rupees. The RBI received dollars.
In return, banks got rupee liquidity while India got foreign exchange.

And for a country that imports a large amount of its energy and other goods, having a large pool of dollars is valuable.

The RBI initially planned the facility for a limited period.

But then something happened. The money came in much faster than expected.

The dollar flood

By August 31, the special facility had attracted $136.38 billion.

And the overwhelming majority came from one source – $127.23 billion through FCNR(B) deposits.

The rest came through overseas foreign-currency borrowings and external commercial borrowings.

The response was so strong that the RBI closed the FCNR(B) window earlier than originally planned.

At the same time, India’s foreign-exchange reserves climbed to a record $740.8 billion by August 28.

And the rupee was responding too.

On September 1, it touched a two-month high, closing at ₹94.95 against the dollar.

By the end of the week, the rupee had gained 0.9%, its strongest weekly performance in five weeks, closing at around ₹94.49/$.

The flood of foreign currency, along with RBI intervention in the foreign-exchange market, was helping support the rupee.

More dollars. More reserves. A stronger rupee.

On the surface, the policy looked like a clear success. But there was something happening on the other side of the transaction.

Because when those dollars came into the RBI…

rupees went out.

The rupee problem

Imagine a bank brings $1 billion to the RBI.

The RBI takes the dollars. The bank receives rupees in return. And the country now has more foreign exchange.

But the banking system also has more domestic currency.

Now imagine that happening at a scale of $136 billion. The numbers start becoming difficult to ignore.

The foreign currency sits with the RBI. The rupees circulate through the financial system. And eventually, there is a lot of cash looking for somewhere to go.

By September 3, surplus liquidity in India’s banking system had climbed to around ₹9.7 lakh crore, according to Reuters, surpassing the previous post-Covid peak.

By the RBI’s September 4 announcement, the figure was around ₹10.3 lakh crore.

That is roughly ₹10 trillion of surplus liquidity. And that changes the behaviour of the banking system.

When banks have more money than they immediately need, they have less reason to pay high rates to obtain funds.

Short-term rates can fall. Money becomes cheaper. Credit conditions can loosen.

And if enough liquidity stays in the system for long enough, it can start influencing the broader economy as inflation starts mounting up.

This is where the RBI steps in.

The RBI wants some of it back

On September 4, the RBI announced a ₹7 lakh crore, 30-day Variable Rate Reverse Repo auction, scheduled for September 7, to suck the excess liquidity from the banking system.

The terminology sounds complicated. The concept isn’t.

Banks have excess cash. The RBI offers them an opportunity to park some of that cash with the central bank for a period.

The banks earn a return. The RBI temporarily takes that money out of circulation.

It’s essentially a liquidity drain. And it wasn’t the only one.

Earlier that day, the RBI had already absorbed around ₹6.02 lakh crore through two shorter-duration VRRR operations.

So, within days, the RBI went from encouraging banks to bring foreign currency into India to encouraging banks to park excess rupees back with the central bank.

The dollars came in. The rupees went out. And now, some of those rupees are coming back.

But why did so much money come in?

This is perhaps the most interesting question. And the answer lies partly in the incentives.

The special facility made it attractive for banks to raise foreign-currency funds.

For NRIs, FCNR(B) deposits offered an opportunity to earn returns on foreign-currency deposits without taking the same direct currency exposure as converting everything into rupees.

For banks, the RBI swap provided access to rupee liquidity.

For India, the result was a huge increase in foreign-currency inflows.

Everyone had a reason to participate. And when incentives line up across three sides of a transaction, money can move very quickly.

The scale surprised the market. Reuters reported that the inflows were much larger than the RBI had initially anticipated.

That’s why the facility was wound down early.

The RBI didn’t need to keep offering the same incentive once the objective had effectively been achieved.

And then comes the irony

India has spent years trying to attract foreign capital.

It wants foreign investors, NRI deposits, and global companies to invest.

Large foreign-exchange reserves give the RBI a stronger buffer against external shocks and more room to manage periods of currency volatility.

But capital doesn’t disappear once it enters the country. It has consequences.

The $136 billion didn’t simply sit in a vault.

The dollars strengthened India’s external position. But the rupees they released were now circulating through the domestic financial system.

And suddenly, the central bank had another problem to manage.

This is the part of monetary policy that rarely makes the headline. One policy decision can solve one problem while creating another.

The RBI wanted more foreign currency. It got it.

That created more rupee liquidity. Now it has to manage that.

India's financial system is getting bigger

And this episode is a useful snapshot of how large India’s financial system has become.

Money can move across borders. NRIs can move billions through deposit programs.

Banks can access overseas funding. The RBI can exchange currencies through large-scale swaps.

Foreign-exchange reserves can move by tens of billions. And liquidity can shift by several lakh crore in a matter of weeks.

The numbers are enormous. But the underlying idea is surprisingly simple.

Money moves.

And whenever money moves at scale, something else moves with it: exchange rates, interest rates, credit, asset prices, and ultimately, economic activity.

That’s why central banks spend so much time watching something most people never think about: liquidity.

Not because ₹10 lakh crore is inherently good or bad.

But because where money sits can matter almost as much as how much money exists.

The Real Balancing Act

India's foreign-exchange reserves are now around $740.8 billion.

That's an extraordinary buffer. It gives India greater protection against external shocks, particularly when the global environment turns volatile.

But reserves aren't the end of the story.

The RBI still has to balance them against domestic liquidity, interest rates, inflation, credit growth and the value of the rupee.

And that balancing act is likely to become increasingly important as India's financial system gets deeper and more connected to global capital.

Because the challenge for a large economy isn't simply: “How do we get money?”

It's also: “What happens after it arrives?”

Sometimes, the most interesting financial stories aren't about a shortage of money. They're about what happens when there is too much of it.

Until Next Sunday!
Disclaimer: This update is for informational purposes only. Please consult a SEBI-registered advisor before investing.

Enjoyed this week’s Sunday Shots? Share it across WhatsApp, LinkedIn, or X — and invite someone else into the conversation.
Subscribe to Sunday Shots for a fresh perspective delivered every week.

Recent Blogs

Subscribe to Journie Shots — thoughtful, well-curated insights and market stories delivered every Sunday.