Journie WealthTech Private Limited | AMFI Registered Mutual Fund & SIF Distributor (ARN: 318048)
From Skyline to Portfolio: A New Phase in India’s Real Estate Story
India is not just building more real estate. It is changing how that real estate gets owned.
For decades, owning Indian real estate usually meant buying a property: a building, an office or a piece of land.
Large capital. Low liquidity. One location. One set of tenants.
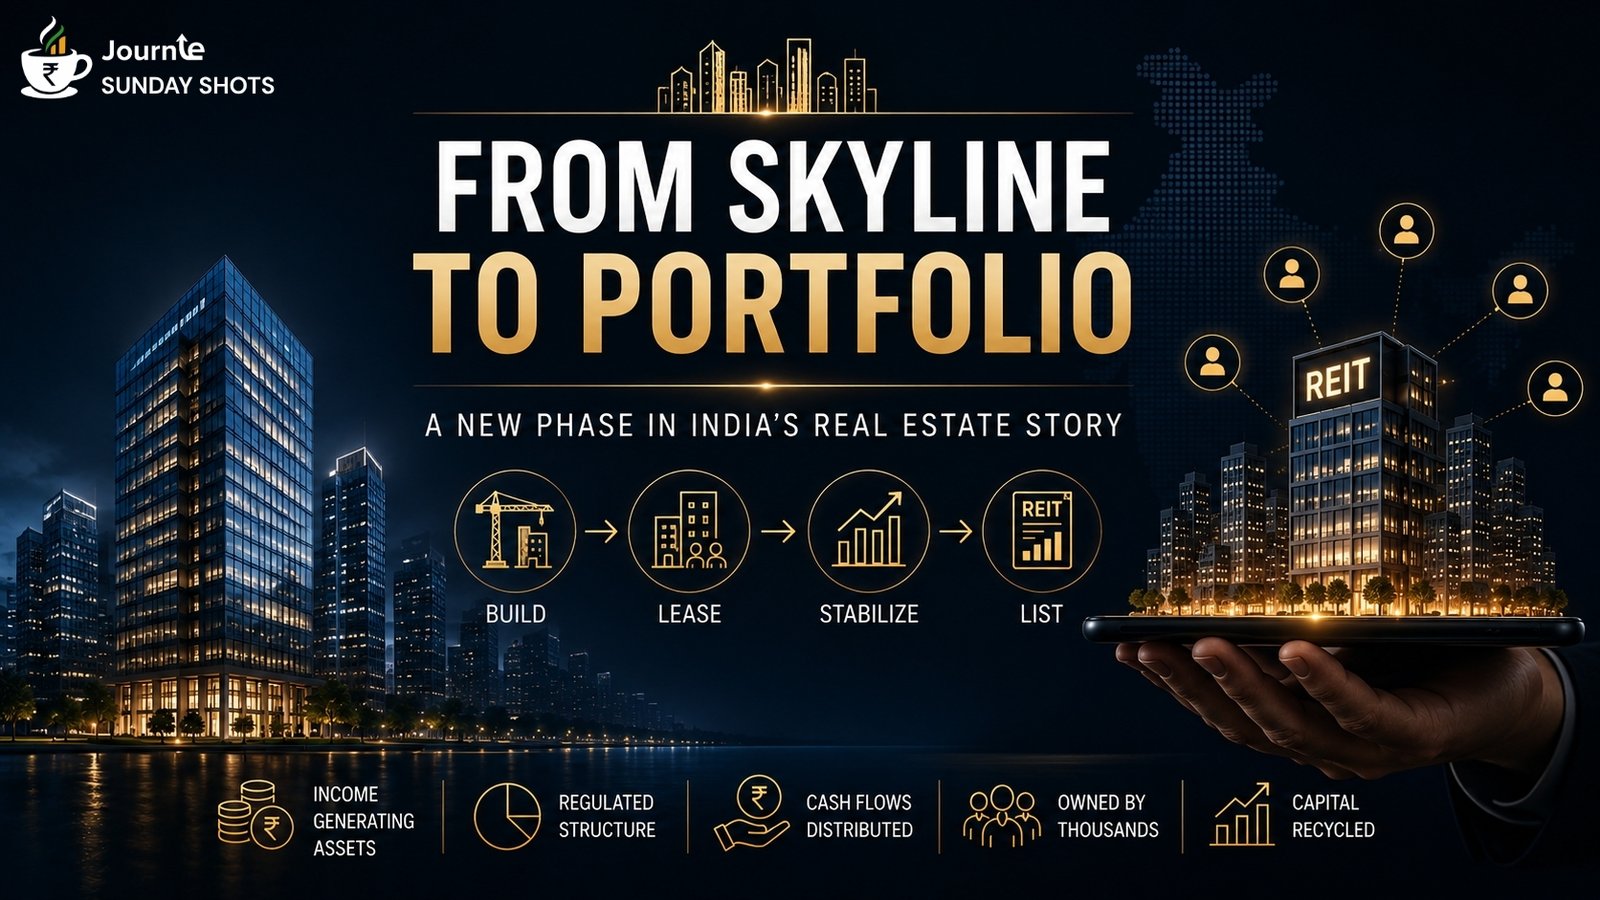
But there is another model emerging: Build → lease → stabilize → list.
That building can now become part of a REIT — and suddenly, an asset worth thousands of crores can be owned through small, tradable units.
This is the financialization of India’s skyline. At the centre of this shift is the growing REIT market in India.
From buildings to financial assets
A Real Estate Investment Trust, or REIT, allows investors to own a share of income-generating real estate without having to buy the property themselves.
Tenants pay rent. The properties generate cash flow. The REIT distributes a large portion of that cash flow to its investors.
India’s regulations require at least 80% of a REIT’s asset value to be invested in completed, revenue-generating properties, while at least 90% of its net distributable cash flow must be distributed to unitholders, subject to applicable regulations.
So unlike speculative land, the underlying asset is designed to generate recurring income.
India doesn’t have a small real estate market. It has a relatively young listed real estate market.
The first Indian REIT was listed only in 2019. Today, there are six listed REITs with roughly ₹3.1 lakh crore of real estate assets and a combined market capitalization of more than ₹2.1 lakh crore.
Yet only a relatively small share of India’s Grade-A office stock is currently REIT-listed.
That leaves a much bigger question: What happens when more of India’s institutional real estate becomes investable?
The next REIT may already be standing
There is an interesting capital cycle happening underneath this.
A developer builds an office park. It leases the property.
Once the asset matures and generates steady rental cash flows, it can potentially be transferred to a REIT.
The developer gets capital back. That capital can fund the next project.
The REIT gets a mature, income-generating asset. Investors get access to the rental economics.
So the cycle becomes:
Developers build → REITs acquire → capital gets recycled → developers build again.
This is important because future REIT growth doesn’t necessarily have to come from existing properties becoming more valuable. It can also come from more properties entering the listed ecosystem.
JLL, a global commercial real estate services and investment management firm, estimates the opportunity across REIT-worthy office and retail assets in India’s top seven cities at around ₹10.8 trillion.
And India's economic growth is feeding the machine
Consider the humble office building.
It doesn’t look particularly exciting. But behind it could be a GCC employing thousands of engineers, analysts and technology professionals.
As India’s economy becomes more corporate, urban and institutional, demand for high-quality commercial real estate grows with it.
GCCs are becoming an increasingly important source of Grade-A office demand. Colliers, a global real estate services and investment management firm, expects GCCs to account for nearly half of India’s office demand in 2026 and 2027.
The thesis isn’t simply: “Property prices will go up.”
It is: India’s economic growth requires more institutional real estate — and that real estate can increasingly become a financial asset.
But how do REIT investors actually make money?
There are three engines.
- Rent
The underlying offices and retail assets generate rental income.
- Rental growth
Leases can have built-in escalations, while new leases can be signed at higher market rentals. Higher occupancy and higher rents can increase the cash generated by the portfolio.
- Valuation
REIT units trade on the stock exchange.
So, their prices can rise or fall depending on interest rates, property values, growth expectations and investor sentiment.
A REIT is not an FD with a property underneath it. You can have a well-occupied building and still see the REIT’s market price fall.
Interest rates are particularly important.
When rates rise, competing fixed-income yields become more attractive and REIT valuations can come under pressure. Higher borrowing costs can also affect acquisition economics.
When rates fall, the opposite can happen.
So the return isn’t simply: rent = return.
It is: rent + rental growth + valuation movement.
Six REITs. Six different businesses.
India’s listed REIT market isn’t one homogeneous asset.
Embassy and Mindspace are heavily exposed to office parks. Nexus brings a significant retail component. Others have different geographic footprints, tenant mixes, leverage and acquisition strategies.
For example, the six REITs currently show occupancy levels ranging from roughly 90% to 99%, while loan-to-value ratios range from about 4% to 31%.
So simply looking at the headline yield doesn’t tell the whole story.
You need to look at: occupancy + rental growth + leverage + tenants + geography + sponsor + acquisition pipeline.
Which creates another problem.
How do you own the opportunity without having to pick the winner?
Real estate enters the mutual fund world
This is where the recent evolution matters.
Edelweiss has launched the Edelweiss Nifty REITs & Realty Index Fund, tracking the Nifty REITs & Realty Total Return Index.
Today, the index is roughly: 60% REITs + 40% realty stocks.
It holds up to 15 securities, uses free-float market capitalization for weighting, and is rebalanced quarterly. The REIT allocation can increase as more eligible REITs are listed.
But the interesting part isn’t really the fund itself. It’s what the fund represents.
Real estate is moving another step away from being something you simply buy physically.
It can now move through a chain:
Property → REIT → Stock Exchange → Equity Index → Mutual Fund
And the regulatory system is moving in the same direction.
From January 2026, SEBI reclassified REITs as equity-related instruments for mutual funds and specialized investment funds, helping open the asset class to a broader pool of institutional capital.
REITs also became eligible for inclusion in equity indices from July 2026.
The building hasn’t changed. The pool of capital that can own it has.
But this isn't a one-way bet
REITs still carry market risk.
Interest rates can hurt valuations. Economic slowdowns can affect leasing. Tenants can leave. Occupancy can fall. Debt can become more expensive. And a portfolio of commercial properties is still exposed to the fortunes of the underlying cities, sectors and tenants.
The Edelweiss fund itself is classified Very High Risk.
So, the opportunity isn’t about replacing FDs or bonds.
It’s about understanding where REITs sit in a broader portfolio.
Perhaps the most interesting thing about India's REIT story isn't the distribution yield.
It is who gets to own India's commercial economy.
For years, the answer was largely: developers, institutions and large property owners.
Now that ownership can increasingly be fragmented across thousands of investors.
You don't need to own the office tower. You can own a piece of the cash flows generated by it.
And as more of India's physical infrastructure moves into listed structures, that distinction becomes increasingly important.
From owning property to owning a portfolio of properties. From owning one building to owning a piece of India's property economy.
India is building the skyline. REITs may determine how widely that skyline gets owned.
See you next Sunday for another shot of insights!
Disclaimer: This update is for informational purposes only. Please consult a SEBI-registered advisor before investing.
Enjoyed this week’s Sunday Shots? Share it across WhatsApp, LinkedIn, or X — and invite someone else into the conversation.
Subscribe to Sunday Shots for a fresh perspective delivered every week.