Journie WealthTech Private Limited | AMFI Registered Mutual Fund & SIF Distributor (ARN: 318048)
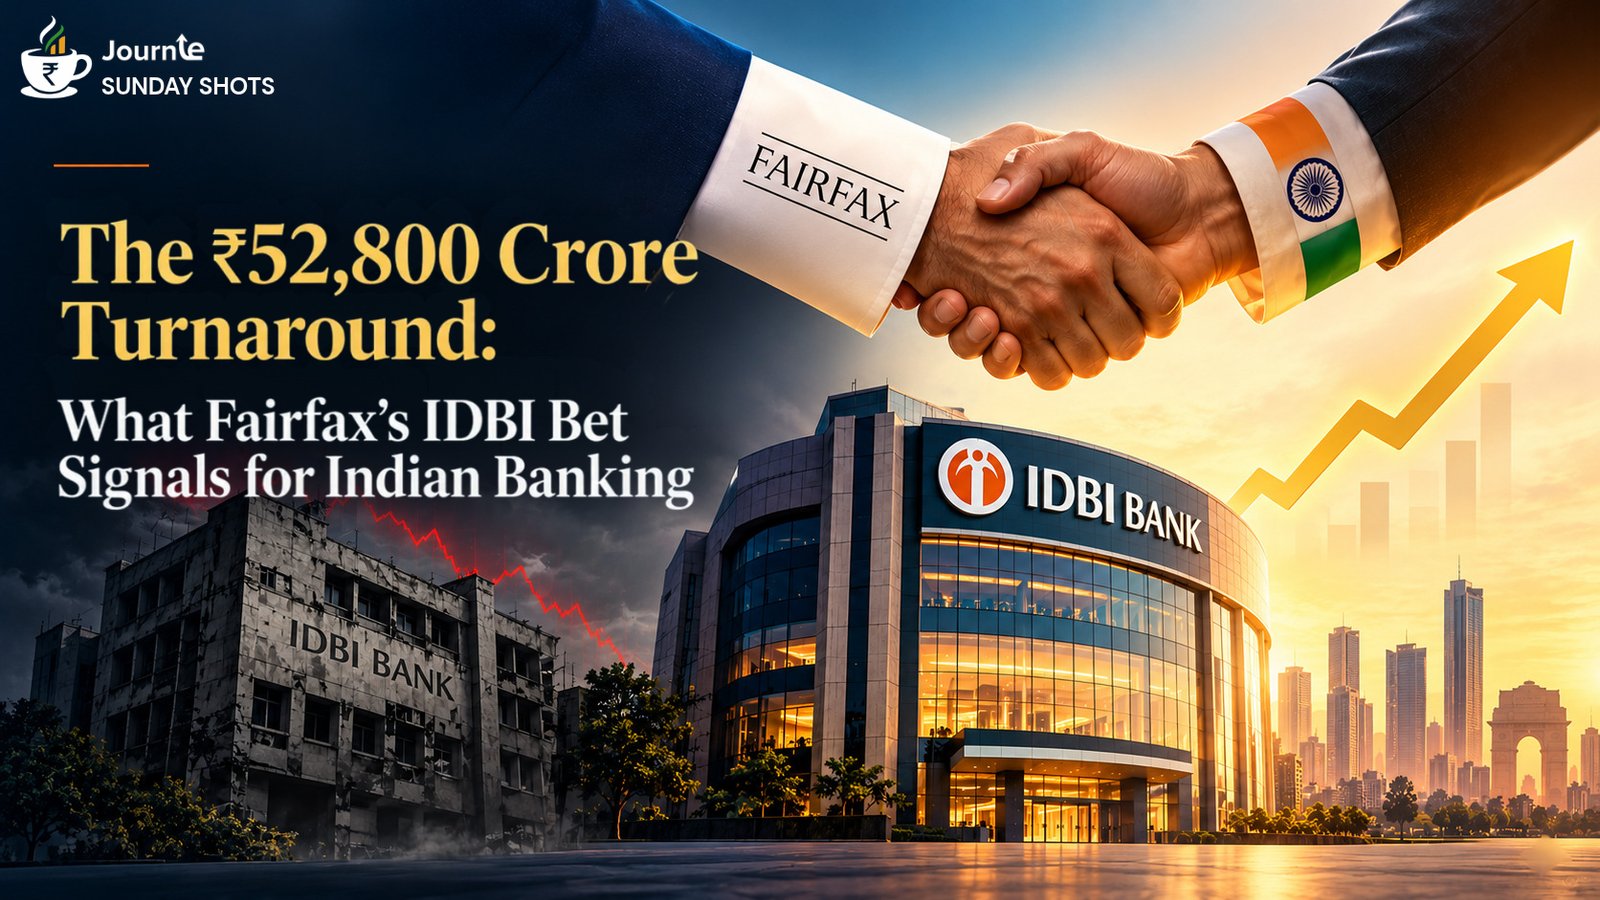
The ₹52,800 Crore Turnaround: What Fairfax’s IDBI Bet Signals for Indian Banking
A bank that once struggled with bad loans is now attracting a ₹52,878 crore acquisition bid.
On October 14, 2026, the Indian government approved Fairfax Financial Holdings as the strategic buyer for a 60.72% stake in IDBI Bank.
But this is more than a bank changing hands.
From RBL Bank and Yes Bank to Shriram Finance, international investors are making significant bets on India’s financial-services industry.
Why are global investors buying into India’s financial system? And what does this mean for the future of Indian banking?
Let’s look beyond the headlines.
From a Troubled Bank to a ₹52,878 Crore Deal
In September 2018, IDBI Bank was in serious financial distress. Nearly one-third of its loan book was bad, with a gross non-performing asset (NPA) ratio of 31.78%.
Under the RBI’s Prompt Corrective Action (PCA) framework, the bank had required repeated capital support from the government and LIC.
Fast-forward to March 2026.
IDBI Bank’s gross NPA ratio had fallen to 2.32%, while its net NPA ratio stood at just 0.15%. For FY2025–26, it reported a net profit of ₹9,513 crore, up 27% year-on-year.
The turnaround was substantial and set the stage for one of India’s biggest financial deals.
The institution that once needed support had become an acquisition target for a global investor willing to pay ₹52,878 crore for a controlling stake.
The government and LIC are selling 30.48% and 30.24%, respectively, transferring a combined 60.72% interest to Fairfax’s acquisition vehicle.
The transaction still requires the remaining regulatory and completion steps.
The interesting question is not just how IDBI recovered. It is what a new owner believes it can do with the bank next.
What Is Fairfax Really Buying?
Fairfax isn’t treating IDBI as a standalone lender.
The group proposes integrating its existing holdings: Go Digit Insurance and IIFL Capital Services, into the IDBI Bank fold, subject to regulatory approvals.
If implemented, the broader structure could bring banking, insurance and capital-markets businesses closer together.
Think of it as buying an entire financial ecosystem rather than a single office building.
A bank gives you low-cost deposit gathering, lending capabilities, and millions of retail relationships.
Bringing banking, insurance and capital-markets businesses closer together could create cross-selling opportunities and allow the group to serve customers’ broader financial needs.
If the proposed structure goes ahead, Fairfax could have the building blocks of a broader financial-services platform.
But bringing businesses under a common ownership structure is only the first step. Whether they can work together effectively and generate better returns is the real test.
Why Are Global Investors Buying Indian Financial Institutions?
IDBI is not an isolated deal; it’s part of a broader wave of foreign capital entering Indian finance:
- RBL Bank: Emirates NBD completed its acquisition of a 60% stake through a primary capital infusion in June 2026.
- Yes Bank: SMBC completed its initial 20% acquisition in September 2025 and signed an agreement for a further 4.2%.
- Shriram Finance: MUFG completed its ₹39,618 crore investment for a 20% stake in April 2026.
These are not identical bets. One gives an investor control of a bank, another builds a strategic minority position, and a third expands exposure to India’s non-bank lending market.
Together, they suggest that global investors see opportunities across different layers of India’s financial system.
So why buy an incumbent instead of setting up a greenfield operation?
- Low-Cost Deposits (CASA): Setting up a retail deposit franchise takes decades. Acquiring a bank grants instant access to cheap, sticky CASA deposits—the ultimate competitive moat in lending.
- Turnkey Distribution: Thousands of physical branches, digital channels, and millions of existing relationships provide immediate scale.
- Regulatory Moats: Banking licenses in India are rare and prized. Buying an existing institution is the fastest route to a full-service license.
- Healthier Balance Sheets: As legacy bad loans have declined across much of the sector, investors can focus more on future credit growth, while still managing the risks that come with lending.
These advantages can make established institutions attractive acquisition targets.
But buying a bank is not the same as creating value from it. The purchase price, competition, cost of funding and ability to execute will ultimately determine the returns.
Is IDBI the Beginning of a Bigger Banking Reset?
The IDBI transaction comes amid renewed discussion about the future ownership and structure of public-sector banks.
Reports indicate plans to trim government stakes in Central Bank of India, UCO Bank, Punjab & Sind Bank, and IOB down to 75% to meet public shareholding norms, along with potential fresh rounds of PSU consolidation.
Separately, the government is reportedly working on another round of public-sector bank consolidation that could identify two more banks for potential privatisation.
There is an important distinction here.
Reducing government ownership does not automatically mean privatisation. The government can sell shares while retaining management control. A strategic sale, by contrast, transfers control to a buyer.
The government has previously announced plans to privatise two public-sector banks in addition to IDBI Bank. However, the latest reports do not amount to a confirmed list of new banks being put up for sale.
The broader policy question is whether India should retain its existing structure of state-owned banks or move towards a smaller number of larger institutions.
Larger banks may benefit from scale, technology investment and operational efficiencies. Consolidation, however, also brings integration risks and potential consequences for competition.
Privatisation and consolidation are different tools. One changes ownership; the other combines institutions.
IDBI’s proposed sale has brought both questions back into focus: who should own India’s banks, and what structure will help them serve a growing economy most effectively?
The Price of a Turnaround
There is one final question worth asking: does ₹52,878 crore represent fair value for IDBI Bank?
Fairfax’s offer of ₹81 per share is approximately 6.6% above the government’s independent valuation benchmark of ₹75.99 per share. Fairfax also said its offer represents a premium of around 23% to the bank’s book value as of June 30, 2026.
While some will debate whether this fully captures the bank’s long-term book value, M&A in Indian banking is rarely just about current asset multiples.
Foreign buyers are paying a strategic premium for control, platform scale, and the multi-decade growth runway of Indian credit.
For Fairfax, the question is whether the value it can create over time justifies the acquisition price.
For the government and LIC, it is whether the sale represents a reasonable realisation of value for the stakes being transferred.
And for the broader market, the transaction offers a useful lesson.
The value of an asset depends not only on what it is worth today, but also on what a capable owner can make of it tomorrow.
India's financial system is attracting international capital as investors look for opportunities to expand through established banks and lending institutions.
IDBI, RBL Bank, Yes Bank and Shriram Finance represent different routes into the same financial ecosystem. Some investors want control. Others want a strategic stake. Some are investing in banks; others are backing non-bank lenders.
But the real test begins after the deal closes.
Can new ownership translate into better products, stronger institutions and sustainable returns? Can investors unlock value without underestimating the complexity of running a financial institution?
IDBI's next chapter will help answer those questions.
Because in finance, an asset gives you ownership. Creating value from it is what makes the investment worthwhile.
Disclaimer: This update is for informational purposes only. Please consult a SEBI-registered advisor before investing.
Enjoyed this week’s Sunday Shots? Share it across WhatsApp, LinkedIn, or X — and invite someone else into the conversation.
Subscribe to Sunday Shots for a fresh perspective delivered every week.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.