Journie WealthTech Private Limited | AMFI Registered Mutual Fund & SIF Distributor (ARN: 318048)
India Had Too Much Money. Now the Price of Money Is Rising.
Something important is happening to money across markets.
India’s banking system had accumulated an unusually large liquidity surplus. Earlier this month, that surplus touched approximately ₹11.16 lakh crore. By September 22, it had fallen to around ₹4.45 lakh crore.
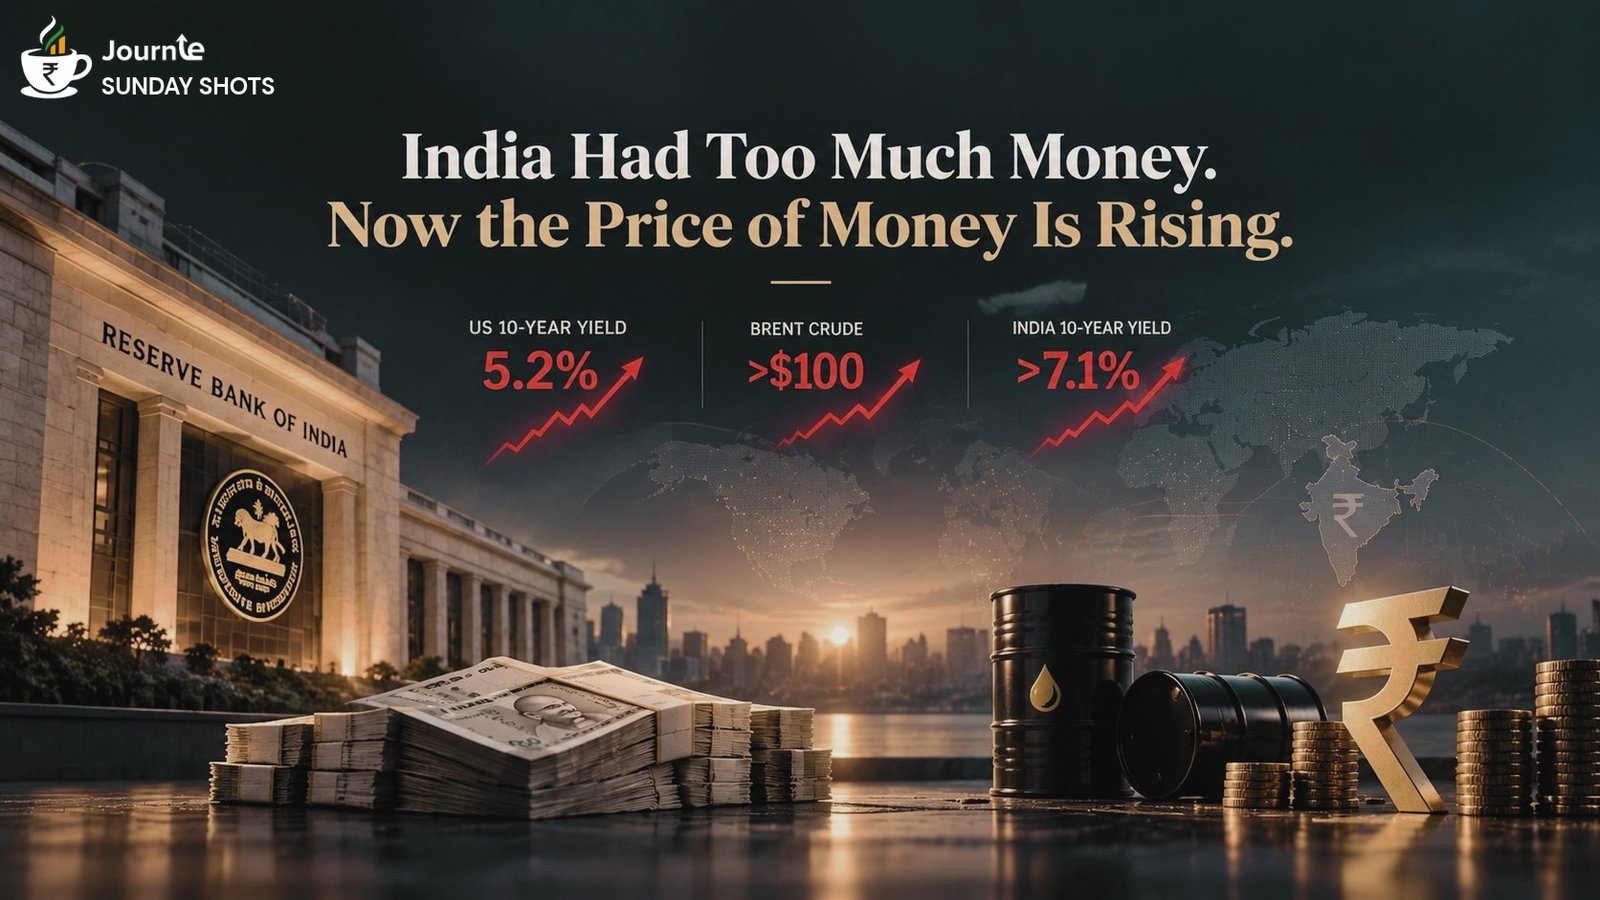
At the same time, the 10-year US Treasury yield crossed 5.2%, Brent crude moved above $100 a barrel and India’s 10-year government bond yield rose above 7.1%.
These are not isolated market moves.
Together, they tell a bigger story: the price of money is changing.
First, India had too much liquidity
To understand what is happening now, we need to go back a few weeks.
India’s banking system suddenly found itself with an extraordinary amount of cash. A major source was the mobilisation of FCNR(B) deposits.
When banks brought the foreign currency raised through these deposits to the RBI’s swap facility, they received rupee liquidity. That increased the amount of cash available in the banking system. Government spending also contributed to the surplus.
By September 6, surplus liquidity had reached approximately ₹11.16 lakh crore — nearly 4% of banking-system deposits.
When banks have that much excess cash, overnight money is easy to find.
Short-term rates tend to remain soft. There is little urgency to pay up for liquidity.
But this was an unusually large surplus, and the RBI did not want all of it to remain in the system indefinitely.
So, it began absorbing the excess.
Then the RBI started absorbing the excess
The RBI announced ₹1 lakh crore of Open Market Operation (OMO) sales in three tranches.
- ₹50,000 crore on September 17, 2026.
- ₹25,000 crore on September 21, 2026.
- ₹25,000 crore scheduled for September 28, 2026.
In simple terms, the RBI sells government securities to the market.
Investors pay for those bonds. Cash moves out of the banking system. Liquidity falls.
The RBI has also been using Variable Rate Reverse Repo (VRRR) auctions to absorb surplus cash.
On September 23 alone, it absorbed ₹75,026 crore through an overnight VRRR operation at a weighted average rate of 5.24%.
The impact has been significant.
Surplus liquidity fell from approximately ₹11.16 lakh crore on September 6 to around ₹4.45 lakh crore by September 22 — a decline of roughly 60%.
That does not mean the RBI alone directly removed 60% of the money. The surplus also changes with government cash flows, foreign-exchange operations and other movements in the banking system.
Still, the direction is clear: Extraordinary liquidity is being normalised.
The first signal appeared in the money market
For weeks, abundant liquidity had kept overnight money relatively easy.
Now, as the surplus shrinks, the RBI is having to actively manage the overnight market within its operating corridor of 5.00% to 5.50%.
The Weighted Average Call Rate — the weighted-average rate in the unsecured overnight call-money market — recently moved above the RBI’s 5.25% repo rate, reaching 5.31% on September 22.
That is an early sign that liquidity is beginning to influence the price at which money changes hands.
And when the price of short-term money starts moving, the impact does not necessarily stop there.
It can travel into bonds, currencies, borrowing costs and eventually the broader economy.
Then bonds started telling a bigger story
By September 24, the benchmark 10-year Indian government bond yield had risen 6 basis points to 7.11%, its highest level since May 21. It opened around 7.13% on September 25 and later settled at approximately 7.12%.
Indian government bonds were also on course for their sixth consecutive weekly loss.
Part of this pressure is coming from the RBI’s liquidity operations.
Think about the mechanics.
When the RBI sells government bonds, investors pay for those securities. That can reduce rupee liquidity in the banking system and put pressure on bond prices.
And when bond prices fall, yields rise.
But liquidity isn’t the whole story.
Oil prices have risen. Inflation concerns have returned. The rupee is under pressure. And expectations around the RBI’s future interest-rate path have changed.
So, the more accurate conclusion is not: Bond yields are rising because the RBI is draining liquidity.
It is: RBI’s liquidity withdrawal is one part of a broader tightening in financial conditions.
And that brings us to the other side of the world.
The world is repricing money too
India’s liquidity story is domestic. But the pressure on the price of money is global too.
The 10-year US Treasury yield crossed 5.2% this week, its highest level since 2007.
The rise reflected concerns around inflation, interest rates and the outlook for longer-term borrowing costs. The 30-year Treasury yield also moved sharply higher, adding to the pressure across global bond markets.
One of the biggest factors has been oil.
Brent crude moved above $100 a barrel as fears of supply disruptions in the Middle East intensified. Prices were volatile, with Brent crude settled at approximately $106.60 a barrel on September 24 and remained around $105 on September 25, as markets continued to assess Middle East supply risks.
A sustained oil shock can lift headline inflation and inflation expectations. That can make central banks less comfortable easing policy aggressively.
When investors expect rates to remain higher for longer, bond yields tend to rise.
US Treasury yields matter far beyond America because they are a key reference point for global borrowing costs, dollar funding conditions and asset valuations.
India feels that pressure
On September 24 and 25, several pressures arrived together:
- US 10-year Treasury yield: around 5.2%.
- Brent crude: around $105–106 a barrel.
- Indian rupee: ₹95.96 per US dollar at the September 24 close.
- Indian 10-year government bond yield: 7.11% on September 24 and ~7.12% on September 25.
- Nifty: down 1.64% on September 24.
- Sensex: down 1.67% on September 24.
Indian equities fell sharply on September 24, while bonds and the rupee also came under pressure. On September 25, equities stabilized somewhat, but crude and global bond yields remained elevated.
It would be tempting to blame all of this on India’s liquidity withdrawal.
But that would be too simple.
The equity sell-off was also driven by higher crude, rising US yields, rupee weakness and sector-specific pressures, particularly in financials following proposed changes to insurance commission rules.
So, the market move reflected several forces arriving at the same time, not one single trigger.
India’s financial markets are being affected by both domestic liquidity conditions and the global price of money.
That may be the most important takeaway.
A few weeks ago, the question was: Why does India have so much liquidity?
Now the question is becoming: What happens when that excess liquidity is removed while the global cost of money is rising?
The answer is beginning to show up across markets.
Overnight rates are moving closer to the policy rate. Government bond yields are rising. The rupee is feeling pressure. Equities are becoming more sensitive to global rates and crude.
None of these moves happens in isolation. Several prices of money are being repriced at the same time.
Money moves across markets.
And when the benchmark price of money changes in one part of the world, it can eventually change the economics of capital somewhere else.
Until next Sunday!
Disclaimer: This update is for informational purposes only. Please consult a SEBI-registered advisor before investing.
Enjoyed this week’s Sunday Shots? Share it across WhatsApp, LinkedIn, or X — and invite someone else into the conversation.
Subscribe to Sunday Shots for a fresh perspective delivered every week.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.